
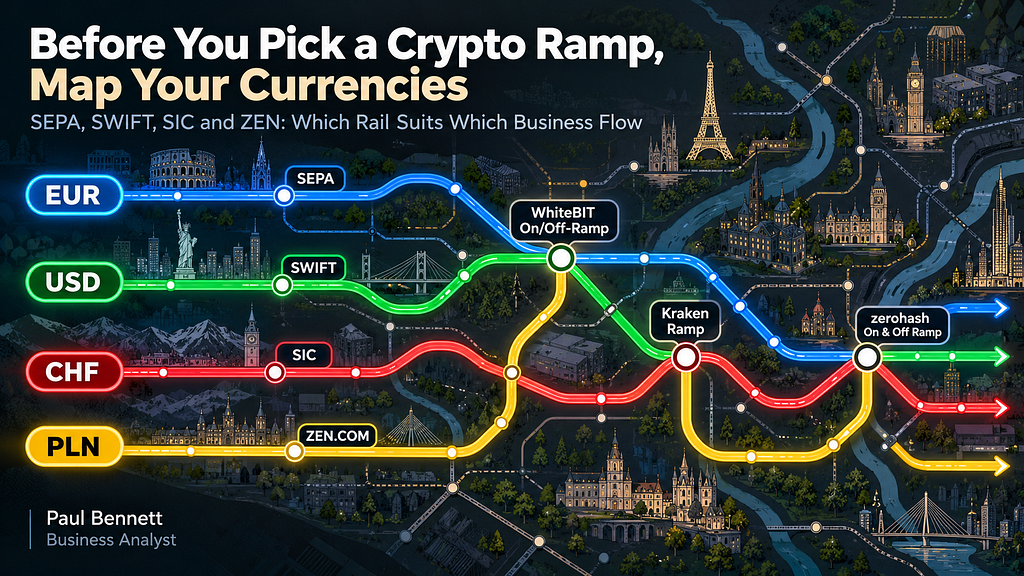
Stablecoins accounted for 60% of crypto purchase value processed through Mercuryo’s on-ramp in H1 2026, up from 43% six months earlier. Meanwhile, accepted stablecoin off-ramp transactions grew 446% year on year, based on the company’s on-ramp report and off-ramp data.
These figures come from one provider, not the entire market. Still, they highlight something worth discussing: how money moves between bank accounts and crypto platforms.
If I were managing those flows for a business, I’d start with two questions. Which currencies are we moving, and where are our bank accounts? The answers help determine which payment routes make sense.
So, What Does Each Payment Route Actually Do?
A company with European partners, a Swiss bank account and international USD settlements might use several payment routes, even through the same crypto platform.
SEPA — for EUR transfers across Europe. It connects participating banks across the Single Euro Payments Area and supports euro transfers between eligible accounts.
SWIFT — for international bank transfers. A global financial messaging network used for cross-border payments in USD and other currencies. Costs and timing depend on the banks involved.
SIC — for Swiss franc transfers. Switzerland’s interbank clearing system handles CHF payments between participating financial institutions.
ZEN.COM — for local PLN payments. Unlike SIC, ZEN.COM is a payment provider rather than a clearing system. Its local PLN transfers use ELIXIR, with availability depending on the provider’s integration and customer eligibility.
Other routes, including ACH in the US and PIX in Brazil, become relevant when businesses need to serve customers in different markets.
Let’s Look at Three Different Business Scenarios
1. A Polish Fintech Needs Both EUR and PLN
Imagine a fintech in Warsaw receiving euros from European partners while paying local expenses in Polish zloty. It needs both currencies and a way to move funds into and out of crypto.
WhiteBIT On/Off-Ramp could be worth considering. It lists EUR transfers through SEPA and PLN through ZEN.COM within one crypto ecosystem.The fee for EUR deposits and withdrawals is a flat €5, while limits depend on KYB level and agreed conditions.
The service also lists USD via SWIFT and CHF via SIC, alongside TRY, GEL and AUD among its supported currencies. Routes for those additional currencies require separate confirmation.
For this fintech, having several fiat options in one place could simplify treasury operations. I’d first confirm which PLN transactions are available to its legal entity and whether the limits suit its volumes.
2. What If Your Wallet Serves Customers Across Different Markets?
Now imagine a wallet provider that wants customers to buy and sell crypto directly inside its app. Some users pay in EUR, others prefer cards or local payment systems. The company needs an integrated payment experience across its supported markets.
Kraken Ramp, also marketed as Payward Ramp, takes this approach. Its institutional offering lists 24+ payment methods, including SEPA, ACH, PIX, debit cards, Apple Pay and Google Pay. The service offers API and SDK integration, with payment processing, compliance and crypto conversion handled through Kraken’s infrastructure.
The attraction is the combination of local payment methods and embedded crypto access. However, supported methods differ by market, and the company would need to confirm which currencies, countries and transaction directions are available to its customers.
For this type of wallet, the integration experience matters alongside currency coverage. A payment method listed on a product page is useful, but the full customer journey — from funding to completed conversion — needs to work in the intended markets.
3. And What About Thousands of USD Payouts?
Imagine a US fintech where customers convert digital assets into dollars and withdraw funds to their bank accounts. With thousands of payouts, settlement speed and integration become important.
zerohash On & Off Ramp supports fiat-to-crypto and crypto-to-fiat conversions through ACH, RTP, SEPA and payment service providers. It also supports 100+ digital assets, with availability depending on the market and integration.
For this business, I’d check which USD payout methods are available, how returned payments are handled and whether prefunding is required. These details can make a big difference when customer withdrawals are part of everyday operations.
So, What Would I Check Before Choosing?
I wouldn’t rank these payment routes from best to worst. A longer currency list doesn’t necessarily mean a better setup, especially when availability depends on jurisdiction, account type and banking partners.
I’d start by checking three things: which currencies and payment methods are actually available, whether the money belongs to the business or its customers, and how much each completed transfer costs.
Processing times matter too. Domestic real-time payments may suit frequent customer withdrawals, while international transfers can work well for corporate treasury operations. Fees, conversion spreads and reconciliation requirements should all be part of the calculation.
Finance can map currencies and volumes, operations can verify settlement schedules, and compliance can confirm eligibility. Sometimes one provider will cover most needs, while other businesses may benefit from combining several services.
I’d rather check those details upfront than discover halfway through a transfer that the selected route doesn’t work as expected.
Disclaimer: This is not financial or investment advice. Do your own research before making any decisions. Use at your own risk.
Three Companies, Three Fiat Problems, Three Different Ramps was originally published in Coinmonks on Medium, where people are continuing the conversation by highlighting and responding to this story.