
The World Bank has been tracking what it costs to send money across borders for more than a decade, and its latest global average is about 6.4% of the amount sent. That figure is measured on small $200 transfers, the kind families send home, so a company wiring tens of thousands of euros pays a much lower rate. Still, it shows how the industry prices a transfer: as a share of whatever you send, so a bigger payment automatically means a bigger bill.
For a treasury team that moves large amounts, this is what makes planning awkward. You can’t put a percentage into next quarter’s budget without guessing the volumes first, and the guess usually misses in the direction you didn’t want.
One Urgent Payment, Two Ways To Send It
Imagine a company that has just agreed a deal with a supplier outside the EU and has to pay €90,000 by Friday. Finance expects the transfer to cost around a hundred euros and moves on to other things.
🔴On the bank route, the bill builds up piece by piece. The daily online limit is €50,000, so there are two transfers instead of one. Each one picks up a fee of about 0.2% and an intermediary bank deduction of around €40, and converting the euros into the supplier’s currency costs roughly another 1%. Together that’s around €1,100, so the supplier receives less than the invoice, and the company sends a third transfer to cover the gap. In between, the bank asks for documents showing where the €90,000 came from. That’s a normal check, but it lands at the worst possible moment.
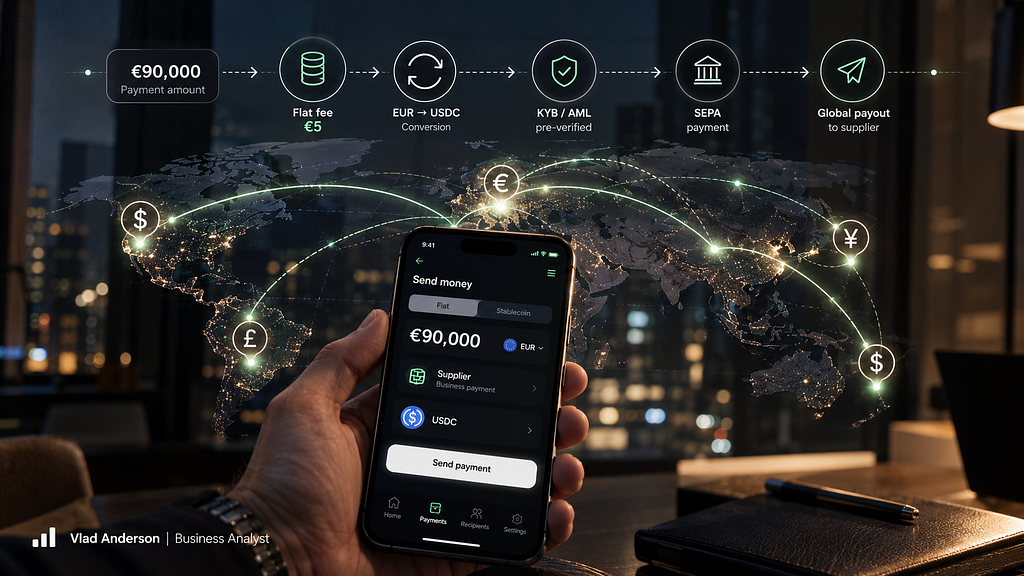
🔴The second route sends the same amount through an on/off-ramp, with the supplier paid in USDC, and this is where flat pricing changes the picture. WhiteBIT On/Off-Ramp, for example, charges institutional clients a fixed €5 on deposits and withdrawals, whether the amount is €500 or €90,000. A single transaction can go up to €100,000 with individual limits. The company’s KYB and AML checks were done once at onboarding, so the payment clears via SEPA with no surprise requests in the middle of the week.
Where the Market Is Heading
Companies are already moving in this direction. McKinsey and Artemis estimate that business-to-business payments in stablecoins now run at about $226 billion a year, roughly 60% of all real stablecoin payments, and that this volume grew more than seven times over the year. They want the same thing as the finance team in our example: a payment that arrives in full and a cost they can name before pressing “send.”
Different providers have built for different parts of that demand. Zero Hash On/Off Ramp, for example, is infrastructure for platforms that want ramps inside their own app. It works with ACH, RTP, SEPA, and PSP rails, covers the whole US with a strong focus on dollar flows, and lets the platform set its own pricing. Bridge Global Payouts, part of Stripe, covers the payouts side: it converts between USD, EUR, MXN, and stablecoins through one API and is designed mostly for companies that pay contractors, sellers, and teams in many countries.
What to Take Into the Next Budget
Before comparing providers, open the last quarter’s payment log and check two things: how many transfers went out and how large they were on average. Percentage pricing gets expensive for companies that send fewer, larger payments, and that’s usually where a flat fee starts to pay off. If you take the three providers I mentioned above, each of them is built around a different payment pattern, so your own log will tell you more than any comparison table. Add the conversion terms on top, and the transfer line in the budget becomes a number you can count rather than guess.
Disclaimer: This is not financial or investment advice. Do your own research before making any decisions. Use at your own risk.
Why Big Payments Still Cost More Than They Should was originally published in Coinmonks on Medium, where people are continuing the conversation by highlighting and responding to this story.