
Author: David Parsons of the TPX Group (London), writing for London Digital Escrow
The consumer internet taught a generation that finding anyone was a search problem. Type a name. Scan ten blue links. Trust the first screen because a machine already decided you should. That machine was never neutral. It knew where you were standing, how old you looked to its model, which ads had been paid, which pages had been stuffed for a crawler, and which brands had bought the right to sit above the answer. That setup is finished as a way for machines to find each other. Not finished as a hobby for people who still browse. Finished as the place an autonomous agent goes when it must find someone, check them, and pay. The agent does not click. It does not linger. It does not feel safer because a logo sat in the sponsored slot. It asks a discovery index for records, reads what they claim, and either goes on or walks away. This is not a gentle change in marketing. It is a change of who decides. For two decades the commercial internet was built around showing people choices. Google ranked links. Amazon ranked products. Dating apps ranked people. Advertising bought attention and brands tried to become the shortcut shoppers trusted. AI agents go further. They let a person hand over the decision itself. The live question is no longer which result appears first. It is whether a human ever sees the other options at all.
From swiping to handing over the choice
The clearest everyday example may come from dating rather than money. Hinge founder Justin McLeod’s new venture, Overtone, is built to move away from endless profiles and swiping. Its software learns about the person and makes a small number of introductions it thinks are worth making. Fast Company reports that Overtone has raised $18 million and is being sold as a modern matchmaking service. The person still decides whether to meet someone. The software does more of the shortlisting. Commerce can move the same way. Instead of asking a search engine for ten hotels, insurers or accountants and comparing them by hand, a user may tell an agent: find the best option inside my budget, my dates and my rules, then book it. The human may only see the final choice. Sometimes they may only see the receipt, i.e. confirmation a transaction has happened.
What the first page actually sold
A search website never sold truth. It sold attention dressed up as relevance. The product was a ranked list tuned to keep a person on the site long enough to be billed. Relevance was the story. The bill was the point. That design made sense when the buyer was a person with a browser. People cannot check every supplier. They use shortcuts. A first-page listing felt like proof. A familiar brand felt like safety. A paid ad felt like importance. Geography, age and inferred sex changed what was shown. Money changed what sat at the top. People can forgive a bad first click, bounce, and try again. An agent about to send money cannot. A bad first pick is not a wasted minute. It can be the wrong lawyer, the wrong supplier, or the wrong account.
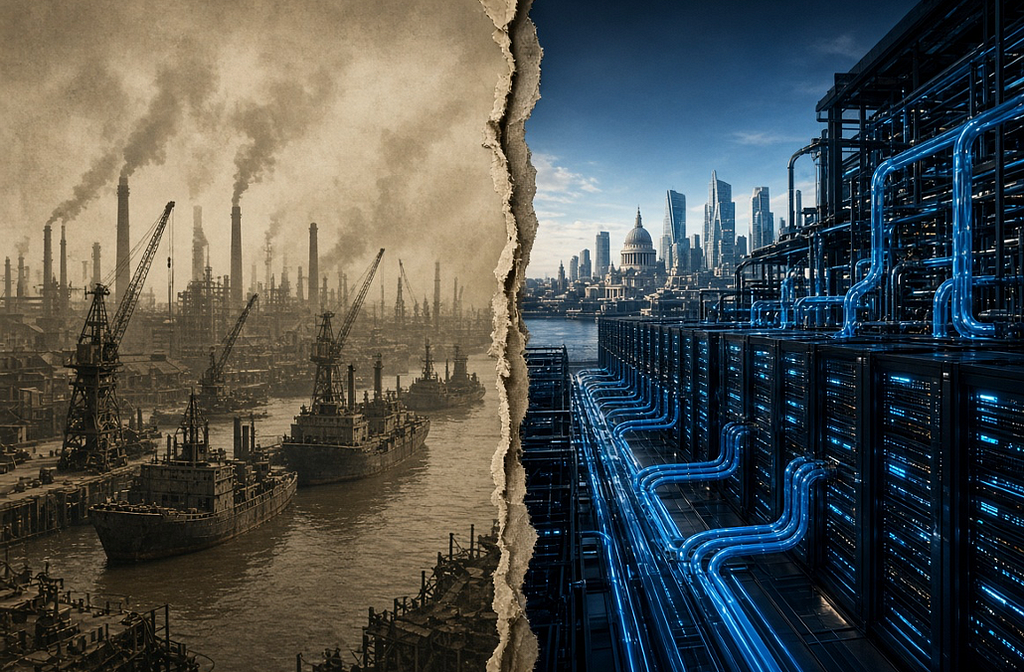
London evolves from a smog ridden trading port to an agentic powered City underpinned by English law
Source: London Digital Escrow
The old levers become a problem
The tools that still run a normal search site are a poor fit for an agent. Where the shopper is standing. How old they look. What sex the model guesses. Whether a page was written for a crawler. How much was paid to sit above the answer. Whether the brand is famous. None of those tell an agent whether the other side is who they say they are, whether they are allowed to do the deal, or whether anyone will pay if the identity is wrong. They tell an agent how a website wanted a human to feel. Feeling is not a control.
What the agent actually asks
An agent looking for a counterparty is not browsing. It is asking a directory of machine-readable records. Who claims they can do this work. In which country. On whose authority. With what proof. With what insurance cover if that proof is wrong. Can we talk now. Can we settle. The owner’s written instructions sit in the middle of that. Those instructions are the new first page. They say what the agent may buy, at what price, in which country, and when it must stop and ask a person. Ranking happens inside those rules, not inside an ad auction. For tiny payments, pennies and small software fees, that can happen with almost no human in the loop. Nobody needs a solicitor on a twenty-four-cent software charge. The risk between the two machines is small. If one of them is badly behaved, the loss is still a rounding error. That changes as the number gets large. A house. A supplier agreement. An investment. A transfer of title. A rogue or badly intentioned agent is no longer a nuisance. It is a legal event. At that size a lawyer is not decoration. They write what the agent may do, they force a person to be present when the amount requires it, and they keep a file a court can read. Size changes how much control you need. It does not change the fact that the agent is no longer shopping from a page of links.
The big payment firms can see this coming
Google has been publishing ways for merchants to describe products and checkout so software can buy without a person walking through a website. Mastercard has talked about letting an agent pay with a card under limits the cardholder set. Visa has talked about telling a shop whether the software at the till is a real agent, who it represents, and whether it has permission to spend. Those projects disagree on how the money should travel. They agree on the problem. Someone has to know who is acting, who allowed it, what it may buy, and how much it may spend. Digital money and tokenised assets only ask the same questions louder, because the money can move in seconds rather than in three working days. Governments will try to write rules for this. They will be late. The spend behind AI systems is already running at a scale that makes a national rulebook look small. See the outlook note on US and UK AI outlays against wartime spend. The practical control, at least for serious deals touching English law, will sit with the people who already know how to name a principal, write an authority, and keep evidence.
Insurance cover is what is left after the facts
On a human website, insurance was often a badge in the footer. A sentence about being covered. That was marketing next to discovery. It was not part of the search. An agent turns that around. It finds a record. It checks who controls the software. It checks the written instructions. Then it asks whether insurance cover exists if those facts were wrong: the keys were not in the hands of the named person, the instructions were exceeded, the other side was not who they claimed. That is why it has to be called insurance cover and not a trust score. A score is another website trick. Insurance cover has a price, a period, and a way to claim. A firm that was easy to find on Google and impossible to insure for identity will lose machine work. A firm that never won the first page, but can be checked and covered, will take work it never won from a search box.
A signed claim can still be a lie
Moving from websites to signed records is not the same as moving from claims to truth. A digital signature can prove who made a statement and whether anyone changed it later. It cannot prove the statement itself is true. A supplier can sign an inflated claim as easily as an honest one. So, discovery needs more than a signature. Professional registers. Independent checks. A way to take a record down. Insurance cover if the facts fail. Trust becomes a pile of things an agent can test, not a feeling about a brand.
Brand and ads do not vanish — they change jobs
Brand will still move people. An owner can even write “only use this name” into the agent’s instructions. What changes is that fame alone may no longer win the machine’s choice. Firms may spend less time pleasing a crawler and more time putting prices, credentials and rules where software can read them. Advertising may change rather than die. The uncomfortable version is that the pitch moves from the shopper to the agent. That makes it more important, not less, to see who is paying for a recommendation.
The first page was stock: the instructions are the market
Google built a huge economy around deciding which choices people saw first. Agent commerce may build a more powerful layer still: deciding which choices people see at all and sometimes buying before they see any. The first page may disappear. The fight moves to the written instructions, the evidence behind a listing, and the insurance cover that sits on the same identity if those facts were wrong. Humans no longer pick the other side at the moment of search. Search engines no longer sell the ranking of that search. What remains is what can be checked: who claims to act, under whose authority, in which country, with what insurance cover, and whether money is allowed to move only after that stack has passed.
Google sold the first page: AI agents will buy without seeing it was originally published in Coinmonks on Medium, where people are continuing the conversation by highlighting and responding to this story.