
Chain of Thoughts 2026–09–14
Core inflation is 2.4% and wages are growing 3.1%, but wheat is up 43% this year and Saudi Arabia’s only remaining export pipeline is still shut. The Fed hikes Wednesday into an inflation no interest rate can reach — which is the clearest available clue about what the hike is actually aimed at.
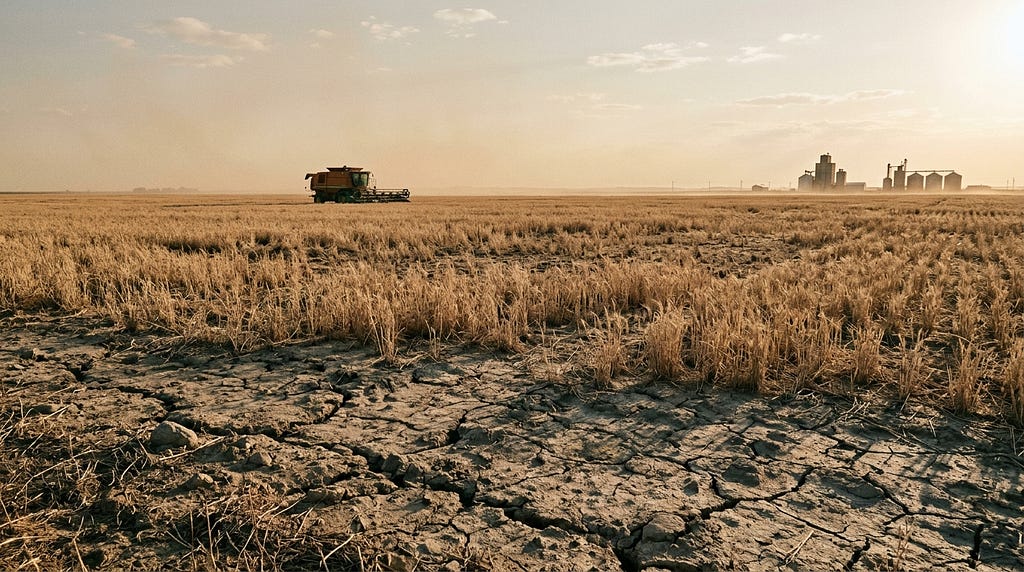
Generated using Nano Banana 2
The Verdict
Bitcoin — short term (3–5 months). $77,132, down 0.28% — a second consecutive weekend session in which crypto was the only venue open to price a live chokepoint event, and a second near-flat print. The map tightened this weekend: CryptoQuant puts bull-market confirmation at $81,700 and identifies $77,100–$80,200 as the band where long-term holders distributed as much as 539,000 BTC across a 30-day stretch this year #8. Spot is on the floor of that band. Beneath it, $70,000 and then $62,000–$65,000, where roughly 476,000 BTC was accumulated. That is better-evidenced than this digest’s $83,000/$72,000 frame, and the honest reconciliation is that $70,000–$72,000 is one zone, not a line.
Bitcoin — long term (1–3 years). The structural case for bitcoin has always been a bet on central-bank carelessness: too much money, too little discipline, a currency debased by institutions that could not stop themselves. That bet has paid. The scenario it does not cover is a central bank that becomes deliberate and decides asset prices are themselves the policy variable — that the froth is the problem, not the symptom. In that world bitcoin is not hedging a monetary error. It is the error, as defined by the people setting the rate. Over three years, the risk worth pricing is not that the Fed loses control. It is that the Fed goes looking for excess and finds it in the most reflexive, most rate-sensitive, most obviously speculative asset on the board.
Ethereum — short term. $2,493.90, down 1.54%, losing the $2,500 handle and extending Saturday’s giveback. That is now two sessions of unwinding Friday’s 4.6% outperformance, which retrospectively confirms it as short-covering rather than accumulation. The $2,300 invalidation sits 7.8% below spot — a cushion that has narrowed by 1.4 points in two days without a single piece of ETH-specific news.
Ethereum — long term. ETH’s demand story has a habit of being borrowed. Every few quarters a new external engine is nominated — AI agents transacting autonomously, corporate treasuries, emerging-market settlement — and every time the measured number lands far below the narrative. TRM examined roughly $52.7 million across 198.9 million x402 settlements and found most of it is not coming from AI agents at all #15. Meanwhile the firms building that demand are buying their own distribution, from Circle’s $400 million purchase of a payments network to Ripple’s pitch of a $13 trillion corporate-treasury opportunity for RLUSD #12. Over three years the ETH case requires that the activity settle on Ethereum. The entities generating it are each quietly assembling the option not to.
Cardano — short term. $0.2061, down 1.05%, giving up the best-relative-performer slot it briefly held on Saturday. Middle of a red board in books thin enough that the ordering carries no information.
Cardano — long term. If the CLARITY Act fails its cloture vote this week, the US regulatory regime for another year is what it has been: enforcement discretion and case law, with clarity manufactured one lawsuit at a time. In that regime the assets with defined status are the ones that were sued and survived, or that regulators explicitly declined to pursue. Cardano has neither — no adverse ruling to have beaten, no favourable one to cite, no settled classification. Being unlitigated is not the same as being safe; it means there is no precedent to stand behind if the question is ever asked. The opposite reading is equally true and worth holding: no litigation also means no enforcement overhang, no legal reserve, no years of discovery, in a cycle where several majors carry exactly that scar tissue. Both are real. Weigh them yourself.
Solana. $100.40, down 1.55%, clinging to the $100 handle with less than half a percent to spare. The level survives the session and nothing more.
BNB and XRP. $719.64 (−2.01%) and $1.35 (−1.89%). BNB was Saturday’s only green major and is Sunday’s worst performer, a 2.5-point swing that says more about weekend exchange-token flow than about anything either chain did.
Why The Market Is Here
Futures put roughly an 85% probability on a rate increase this week. Set that against what the inflation data says: core CPI running near 2.4%, wage growth slowed to about 3.1% year over year, no wage-price spiral, no evidence that the energy shock has embedded itself in second-round effects. An economist made the obvious observation this weekend — that a hike into those numbers serves Wall Street more than price stability, because the one thing a higher benchmark reliably does is widen the spread between what banks pay depositors and what they charge borrowers #1. The counter-argument is real and belongs here: August’s core gains were concentrated in services, with super-core up 0.5% on the month and 3% on the year, which is not a supply-chain number #2.
Now look at where the rest of the price pressure is coming from.
Wheat futures are up 43% since the start of the year, soybeans 24%, corn 20% — the USDA has cut its US harvest forecast twice on heat and drought, and the wheat leg traces to the Black Sea #3. Brent finished the week above $100 for the first time in months, with warnings about heating-oil costs into winter already running #4. Saudi Arabia’s East-West pipeline is still shut, and with Hormuz closed it is the kingdom’s sole crude export route — there is no third option behind it #7. And the Houthis completed their takeover of Yemen’s Red Sea coastline over the weekend, holding ground roughly 20 kilometres from the African shore and with it effective control of Bab al-Mandeb; Egypt lost about $7 billion, some 60% of Suez Canal revenues, during the earlier disruption, and operators now face the Cape of Good Hope as the alternative #5. More than 2,000 Yemenis crossed to Djibouti in twenty-four hours #6.
Here is the point. Rates cannot grow wheat. They cannot repair a pipeline, and they cannot move an island out of a shipping lane. Every one of the four largest sources of price pressure in this economy right now is a supply constraint, and a 25 basis point increase does not touch a single one of them. What a rate increase does reach is the price of money, the price of risk, and the margin on a loan book.
That is not an accusation of bad faith. It is a statement about instruments and targets. A central bank facing supply-side inflation has two honest options: wait, or tighten financial conditions hard enough that demand destruction does the work. The first is politically impossible with crude above $100 and groceries climbing. The second means the operative target is asset prices, and the operative measure of success is that something falls.
Which connects to the frame this digest has been running. The argument all week has been that crypto is priced off the variance around policy rather than the level of it, and that Friday’s 11% volatility crush was a market that had stopped paying for insurance on a settled question. That reading still holds. What changes is the shape of what comes after Wednesday. If the hike answers a CPI print, there is a release valve — a cooler print ends it. If the hike answers financial conditions, there is no data release that stops it, because the input to the reaction function is the market’s own level. Friday priced the end of an argument about Wednesday. It did not price a reaction function with no off switch.
And under that reading crypto is not a bystander. It is the most rate-sensitive, most reflexive, most visibly speculative asset class available to a policymaker who has decided froth is the problem. The 85% is a probability. The objective is the part nobody has priced.
One honest note on the tape. This was the second consecutive session in which crypto and tokenized gold were the only open venues while a chokepoint changed hands, and bitcoin moved 0.28% — a second data point for yesterday’s argument that bitcoin trades around the clock while its marginal owner keeps banker’s hours. It is not a verdict, and the Monday test set out yesterday is not gradeable yet: US markets have not opened and Brent has not printed. Scoring it now would be marking a paper before it was sat.
Institutional Pulse
The ETF number is unchanged from Friday — roughly $462.6 million in net outflows across Sept 8–11 against a $1 billion inflow the week before #18, with no new print over the weekend. Two flat weekend sessions did not change what the flows say.
What did move was the industry’s own capital allocation, and it moved away from holding coins. Circle spent $400 million on a payments network rather than on inventory #11. Bitcoin Suisse is preparing to cut up to half its Swiss workforce and shift the work abroad — a cost-structure decision made while the price is flat, which is when those decisions get made #13. And Nvidia is weighing a $10 billion investment in an Anthropic offering that could raise up to $100 billion at a valuation near $2 trillion #14.
Hold that last number next to a $462.6 million weekly outflow and the scale gap is the story — which brings the OTC point back in a shape it has not had before. Flow data can only count trades that were placed. It has no column for capital that looked at this asset class, priced the alternative, and went to an AI cap table instead. That is not a bearish claim; it is a claim about what a flow number is capable of measuring. The most consequential allocation decision of the weekend generated no crypto volume at all.
Calendar Watch
FOMC, Sept 15–16. Roughly 85% priced for 25bp, a modest softening from the ~90% carried into the weekend. The number to watch in the statement is not the decision. It is whether the language reaches for financial conditions and asset valuations rather than inflation expectations — that would confirm the Wall-Street-not-inflation reading live, on the day.
CLARITY Act, Senate cloture vote Sept 15. The first genuine policy-risk trigger in weeks, so the frame comes off the shelf. Cloture needs 60 votes; Republicans hold 53; the unresolved fights are over ethics rules, stablecoin rewards and illicit-finance provisions, and Galaxy has cut its odds of the bill becoming law this year to around 10% #10. CoinDesk calls it a bill simultaneously alive and dead until someone opens the box #9. The practical consequence is worth stating plainly: crypto is a policy-risk asset with a legislative window shorter than its pricing implies, because a bill that misses cloture this week does not get a second run before the midterms reshuffle the arithmetic.
Bank of Japan, Sept 16–17. USDJPY at 153.55, flat on the week, the day after the Fed. Two central banks in twenty-four hours with the carry trade sitting between them — and a third straight edition where that gets only a calendar line.
Signals Worth Watching
A correction from yesterday, and it reverses the conclusion. This digest reported Friday’s CME gold settlement at $4,366.20, up 0.04%, and built a Signals bullet on it: a haven that could not hold an intraday gain. The final settle was revised to $4,408.90, up 1.02%. Gold held the gain. The bullet was wrong, and the accurate version is its opposite — the metal closed near its highs into a Middle East weekend, which is a bid behaving like fear rather than positioning.
The statement language is the tell, not the decision. Financial conditions, valuations, market froth — any of those in Wednesday’s text means the reaction function has an input the data cannot fix. Inflation expectations and labour slack mean the conventional read still governs.
The cloture count. Not whether CLARITY passes, but how many Democrats cross. A count in the mid-50s confirms the legislative window is closing. Sixty or better and the policy-risk framing goes back on the shelf for the year.
$81,700, and the shelf beneath. Clearing it on a daily close is the confirmation signal with the best evidence behind it; $77,100–$80,200 is where 539,000 coins changed hands on the way down this year, and spot is on the floor of it. Below, $70,000–$72,000 is one support zone, not two levels.
Bab al-Mandeb war-risk premiums. Still near 0.5% of hull value as a standing quote; the trigger remains a move above 1% for general transits, which would mean underwriters have repriced the strait as impassable rather than merely expensive. Watch also whether the Houthis interdict traffic from Mayun or simply hold it — control and closure are different products.
Two de-escalation threads, running against all of the above. Iran is convening talks with Iraq and Gulf states in Oman on shared regional security #17, and the BRICS summit in New Delhi closed with the bloc visibly divided on Iran and Ukraine #16. The first is the only live path to a supply-side de-rating. The second is a reminder that the alternative-order story keeps failing at the point where it has to agree on something.
If I Had $100 This Month
Two flat weekend sessions, a rate decision on Wednesday whose purpose is ambiguous, and a cloture vote on Tuesday on a bill given roughly one-in-ten odds of becoming law this year. This is a week to have a schedule, not a view.
$60 → BTC. Spot is on the floor of the band where long-term holders distributed half a million coins this year, which is a worse entry than it looks and a better one than $81,700.$25 → ETH. Two sessions of giving back a short-covering rally is exactly what short-covering rallies do, and none of it touched the three-year question of where the activity settles.$15 → ADA. An asset with no legal precedent behind it in a year that will probably end without legislation is a small-position asset, and the sizing says so.
Hold actual coins. Not ETF shares, not equity proxies.
This is how I’d think about it. Make your own call.
Sources
#1 — Fed rate hike is about Wall Street, not inflation, says economist — CoinDesk#2 — Core CPI rose a faster-than-forecast 0.3% in August, setting up Fed rate hike — CoinDesk#3 — The price of almost everything on your dinner table is climbing at once — MarketWatch#4 — Oil prices create ‘huge worry’ as winter looms — BBC Business#5 — Red Sea nations watch as Houthis seize Bab al-Mandeb strait — Al Jazeera#6 — More than 2,000 Yemenis flee to Djibouti amid Houthi advances — Al Jazeera#7 — Saudi Arabia shuts critical oil pipeline after drone attack: What it means — Al Jazeera#8 — CryptoQuant says bitcoin must clear resistance at $81,700 to confirm new bull market — The Block#9 — Crypto’s Clarity Act is a Schrödinger’s cat in life-death limbo as U.S. Senate returns — CoinDesk#10 — Crypto enters September with legislative policy gamble hanging by a thread — CNBC#11 — Circle’s $400M Tazapay deal buys emerging market links that take ‘years to build’ — CoinDesk#12 — Ripple stablecoin chief sees $13 trillion corporate treasury opportunity for RLUSD — CoinDesk#13 — Bitcoin Suisse plans to cut up to half its Swiss jobs as it shifts work abroad — CoinDesk#14 — Nvidia considers $10B investment in potential record Anthropic IPO — CoinTelegraph#15 — AI Agents Spending Money Online? New Research Says Not Really — Decrypt#16 — Iran war reshapes Brics ties but also exposes divisions — BBC World#17 — Iran-GCC summit: What’s behind the meeting, why is Bahrain not attending? — Al Jazeera#18 — Bitcoin ETFs See $461M Outflows This Week With Zero Inflows — Coinpedia
Market Data
Asset Price 24h
──────────────────────────────────────
Bitcoin (BTC) $77,132 -0.28%
Ethereum (ETH) $2,493.90 -1.54%
Cardano (ADA) $0.2061 -1.05%
Solana (SOL) $100.40 -1.55%
BNB $719.64 -2.01%
XRP $1.35 -1.89%Fear & Greed: 61 — Greed (was 63 yesterday)
S&P 500: +0.86% · Nasdaq: +0.96% · DXY: 99.12 (+0.03%)
Tokenized gold (PAXG): $4,352 (-0.05%) · Brent: $104.61 (-2.81%)
US 10Y: 4.975% · US 30Y: 5.354% · VIX: 15.84 (-11.21%) · USDJPY: 153.55Weekend edition: S&P, Nasdaq, DXY, Brent, yields and VIX are Friday Sep 11 closes,
unchanged from yesterday’s edition. CME gold’s Friday settle was revised to
$4,408.90 (+1.02%) from the $4,366.20 (+0.04%) reported here yesterday; the gold
row above is weekend-traded tokenized gold. Fear & Greed slipped 2 points.
Chain of Thought is a daily crypto and macro market digest. Not financial advice.
Rates Cannot Grow Wheat was originally published in Coinmonks on Medium, where people are continuing the conversation by highlighting and responding to this story.